Journal · Financce · Saving
Emergency fund: how much you need and how to build it step by step
How to size an emergency fund for your household, where to keep it, and a realistic plan to build it from zero without stalling.
 Goldmend Money
4 min read
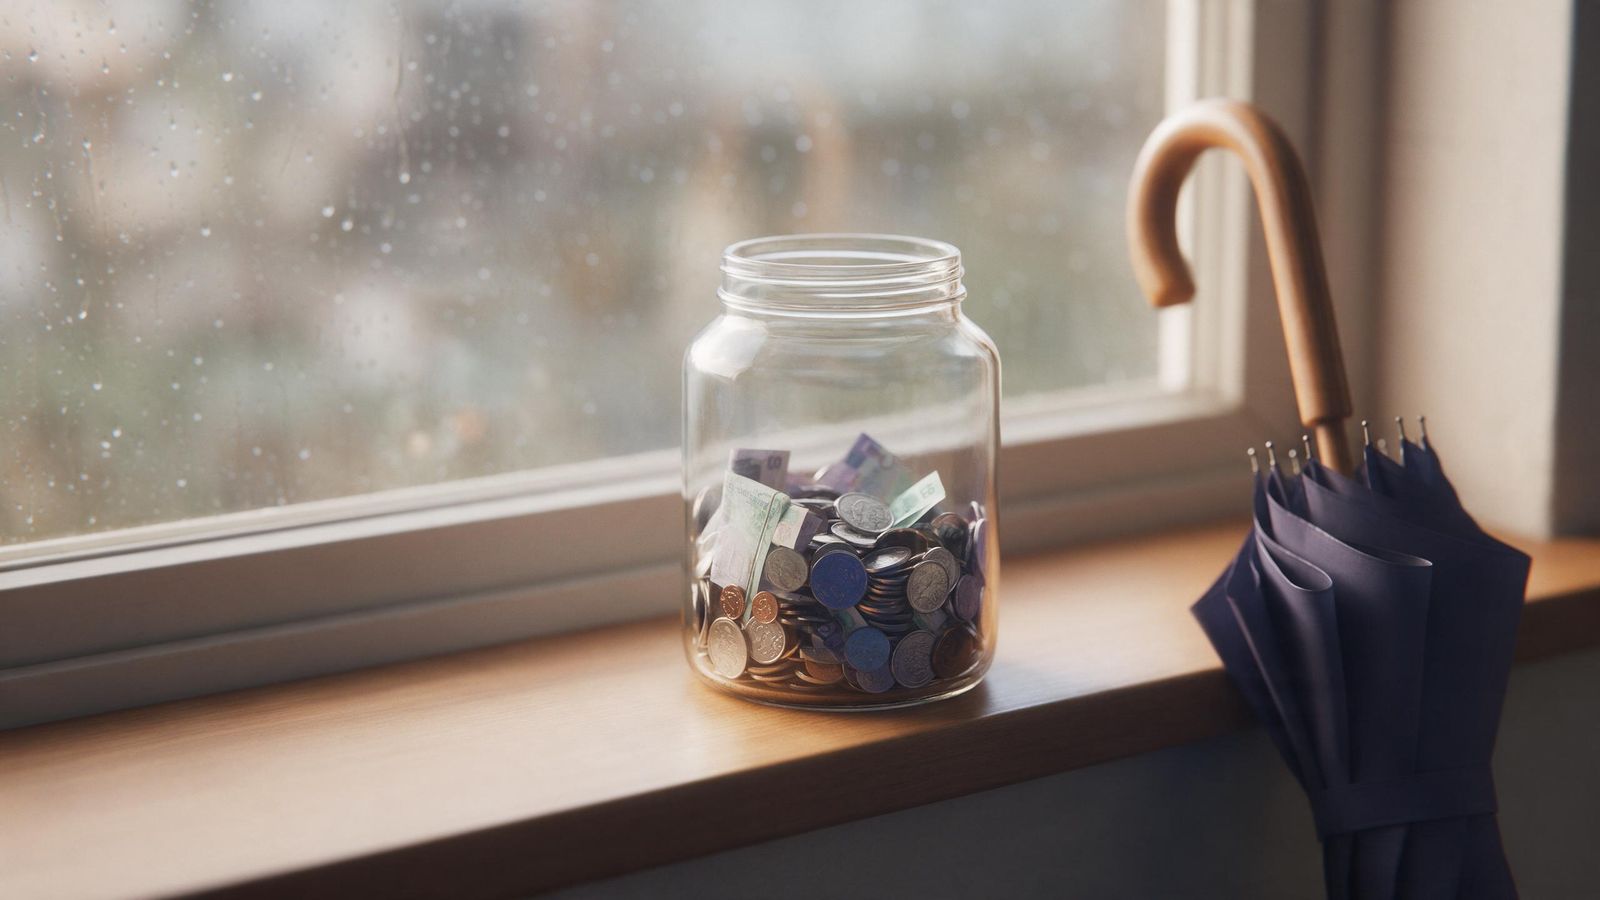
An emergency fund is money set aside for things you cannot plan: losing your job, a hospital stay, a car breakdown, an urgent flight home. Without one, a single bad week ends up on a credit card or a loan from family.
It is not exciting money. It is not meant to grow fast. Its job is to be there, quickly, when you need it.
How much is enough?
A common guideline is three to six months of essential expenses. Notice the word essential. You do not need to cover holidays and eating out. You need to cover what you must keep paying if income stops.
Start by adding up a month of essentials:
- housing (rent or loan)
- utilities, phone and internet
- groceries
- transport
- insurance premiums
- minimum loan and card payments
- school fees and childcare
- regular support to parents, if you give it
Say that comes to S$4,000 a month. Three months is S$12,000. Six months is S$24,000. These figures are examples only.
When to aim higher
Lean towards six months or more if:
- you are the only earner in the household
- your income is irregular, such as commission or freelance work
- your industry is prone to layoffs
- you support parents or other relatives
- you have health conditions that might stop you working
When three months may be enough
You might be comfortable nearer three months if there are two stable incomes, low fixed costs and good insurance cover.
Where to keep it
An emergency fund should be:
- safe — not exposed to big price swings
- easy to reach — within a day or two
- separate — not mixed with your spending account, so you do not dip into it by accident
Many people use a separate savings account or a similar low-risk place. Options and protections differ between countries and providers, so check with your bank and official sources such as MAS in Singapore, Bank Negara Malaysia, Moneysmart in Australia or the CFPB in the USA before deciding. Avoid putting emergency money into anything you might have to sell at a loss.
How to build it from zero
Twelve thousand dollars can feel impossible. Break it down.
Stage 1: a starter buffer
Aim for one month of essentials, or even a smaller round number like S$1,000. This covers most small shocks: a phone repair, a clinic visit, a car battery. Reaching it quickly builds confidence.
Stage 2: three months
Set a monthly amount you can sustain. S$500 a month reaches S$12,000 in two years. S$800 a month gets there in about 15 months. Choose a figure that survives a tight month.
Stage 3: your full target
Once you reach three months, decide whether to keep going towards six or split new savings between the fund and other goals.
Ways to speed it up
- Save on payday. Move the amount the day salary arrives. See the payday routine guide for more.
- Use windfalls. Put part of a bonus, tax refund, angpow money or side income straight into the fund.
- Redirect a finished payment. When an instalment plan ends, keep "paying" the same amount into the fund.
- Cut one recurring cost. Cancelling a S$15 subscription adds S$180 a year.
When to use it, and when not to
Use it for real emergencies: lost income, medical costs, urgent repairs, family crises. Do not use it for sales, planned holidays or a new phone you wanted anyway. Those deserve their own goals.
If you do use it, that is what it is for. Rebuild it the same way you built it.
Try it in Financce
- Go to More → Goals → New goal. Name it "Emergency fund".
- Enter your target amount, such as three months of essentials.
- Add a target date. Financce shows how much to save each month, for example "Save S$600 a month for 20 months".
- Each payday, open the goal and use Add or withdraw to record what you set aside.
- Not sure of your essentials? Check the Reports tab to see what you spend on needs each month.
You can also try the Savings goal calculator in More → Calculators to test different monthly amounts before you commit.
This article is general information, not financial advice.
 Try it in Financce, the Goldmend Money app for everyday money. Get Financce
General information, not financial advice. Figures are examples.
Next: Track subscriptions and bills so nothing surprises you