Journal · Financce · Family money
Family budgeting with kids: tracking costs per child and teaching with pocket money
See what each child really costs, plan for school-term spikes, and use pocket money to teach children how to manage money early.
 Goldmend Money
4 min read
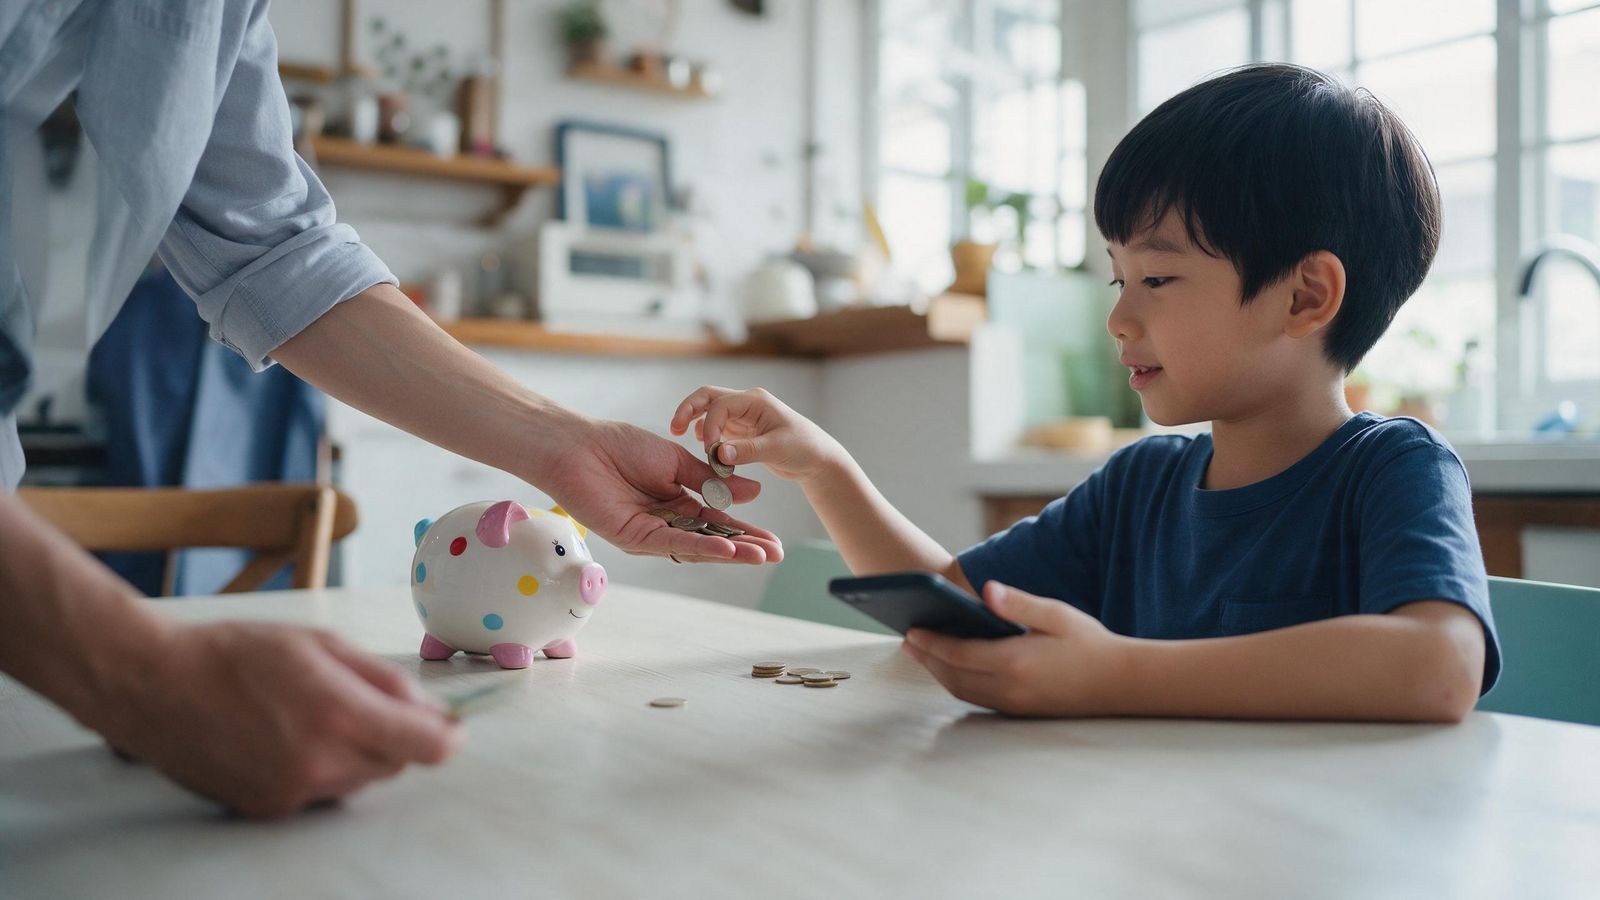
Children change a household budget in ways that are hard to see. There is no single "kids" bill. Instead there are dozens of smaller costs: school canteen money, tuition, uniforms, books, transport, birthday presents, swimming lessons, the extra groceries.
Most parents know the total feels big. Few know where it actually goes, or how much each child costs. Knowing that makes it easier to plan, and to make fair decisions between siblings.
Know what each child costs
Start by tagging spending by person for one or two months. You do not need a perfect system. Just mark who an expense was for when you log it.
After a month or two, you will see patterns:
- which costs are fixed (school fees, tuition, transport)
- which are regular but flexible (snacks, outings, clothes)
- which are lumpy (books at the start of term, festive clothes, school trips)
This often surprises people. One child's weekly activity might cost more than everyone's groceries. That is not wrong. It is just better to know.
Plan for the spikes
The start of the school year, new terms, festive seasons and birthdays all cause spending spikes. In Singapore and Malaysia, January is a common pressure point, with school supplies and uniforms arriving soon after year-end holidays and festive spending. In Australia it falls in late January, and in the USA in August.
Two ways to soften spikes:
- List them in advance. Add known yearly and termly costs as recurring bills, so they show up before they hit.
- Save a little each month. If back-to-school costs about S$900, setting aside S$75 a month means January is covered.
Figures are examples. Your costs will differ.
Pocket money as a teaching tool
Pocket money is not just a cost. It is one of the few ways children can practise managing money with low stakes. A few principles help.
Pick a regular amount and day
Consistency matters more than the amount. Weekly works well for younger children. Older children can handle monthly, which teaches them to plan across a longer stretch.
Be clear what it covers
Agree what the allowance is for. For a primary school child it might be canteen snacks and small treats. For a teenager it might include transport, phone top-ups and outings with friends. The more it covers, the more decisions they practise.
Let them make small mistakes
If they spend everything in two days, resist the urge to top up. Running short with a small amount teaches more than any lecture. The lesson is cheaper at age nine than at twenty-five.
Encourage a split
A simple rule children can follow: some to spend, some to save, and some to share or give. The exact split is up to your family. A clear jar or a separate envelope helps younger children see their savings grow.
Talk about it
Ask what they bought and whether it was worth it. Share, in simple terms, how the family plans money. Children learn far more from watching parents budget than from being told to save.
Keep it fair between siblings
Siblings compare. Tracking costs per child helps you explain decisions. "Your brother's tuition costs more this year, but your swimming costs more next year" is easier to say when you have the numbers.
Fair does not always mean equal. It means each child's needs are seen.
Try it in Financce
- Go to More → Family → Add family member for each child, your partner or parents.
- Enter a Monthly allowance or pocket money for each child, if you give one.
- When you add an expense, choose who it was For. Each person's screen shows what was spent on them.
- Financce compares the allowance with what you record under the Kids category for that child each month.
- Add school fees, tuition and classes in More → Education → Add school fee or class, linked to the right child. You get reminded before they are due.
This article is general information, not financial advice.
 Try it in Financce, the Goldmend Money app for everyday money. Get Financce
General information, not financial advice. Figures are examples.
Next: Supporting your parents while still saving for yourself