Journal · Financce · Family money
Supporting your parents while still saving for yourself
How to give regular support to parents without sacrificing your own emergency fund and retirement, with a simple order of priorities and family tips.
 Goldmend Money
5 min read
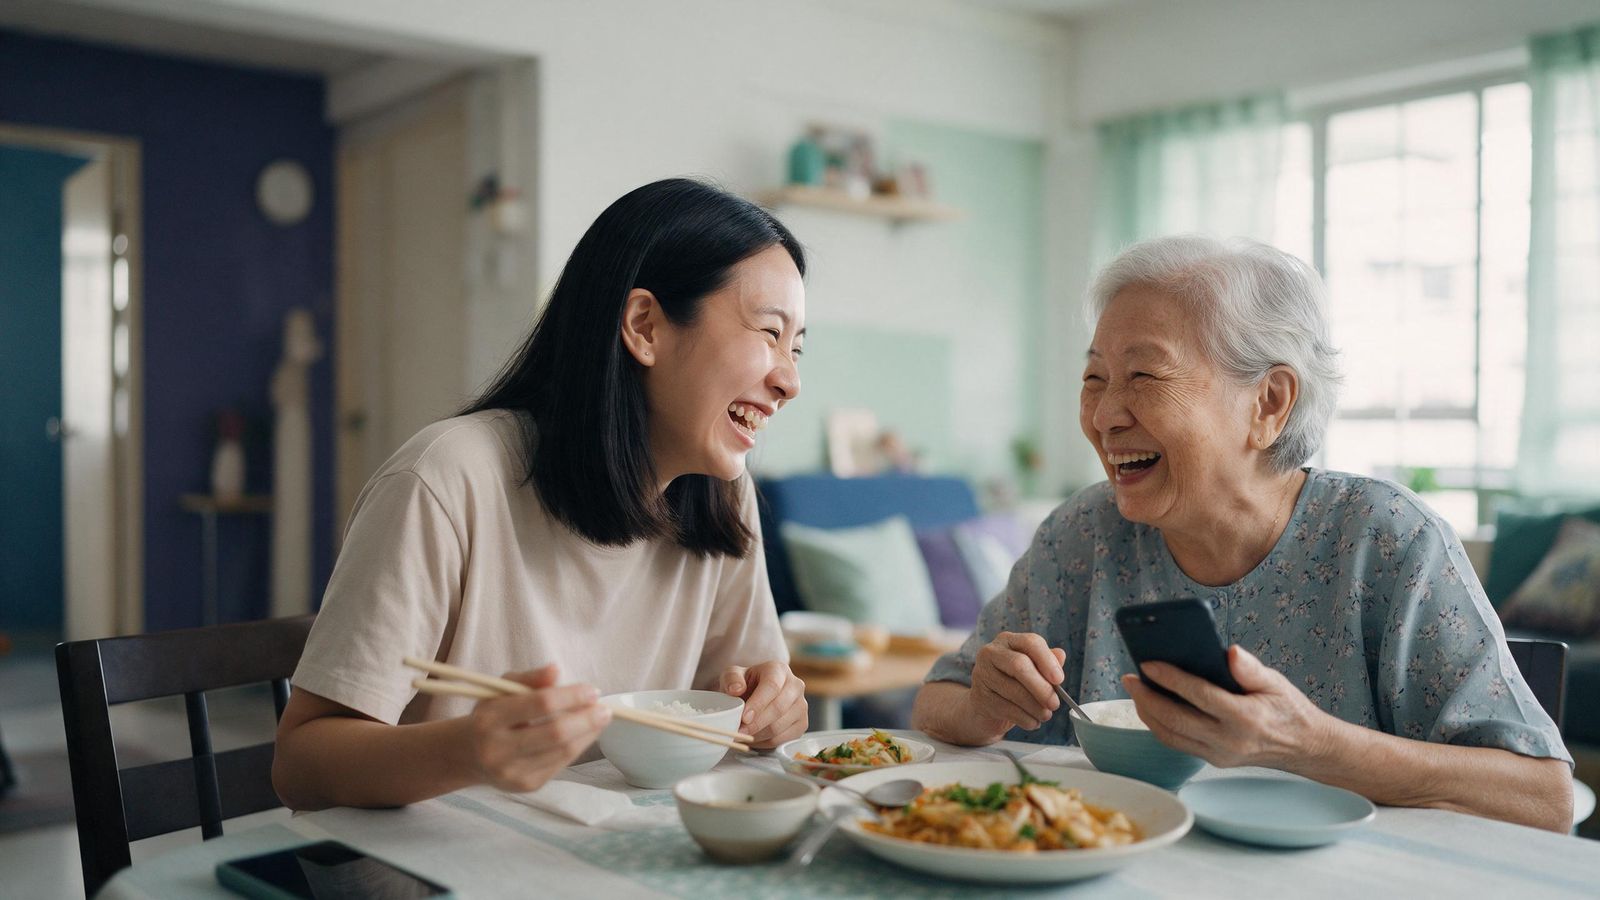
In much of Southeast Asia, giving money to parents is not optional. It is a sign of respect, a family expectation and, often, a real need. Many parents retired with modest savings, and rising living and medical costs make adult children their main safety net.
At the same time, you have your own rent or housing loan, maybe children, and your own retirement to fund. People caught between the two are sometimes called the "sandwich generation". The pressure is real, and it rarely gets discussed openly.
This guide offers a way to give generously and still protect your future.
Why your own savings matter to your parents too
It can feel selfish to save while your parents need help. Think of it differently. If you have no emergency fund, one job loss or hospital stay means both you and your parents lose support at the same time. If you reach retirement with too little, your own children may face the same squeeze.
Protecting your finances is part of protecting theirs.
Step 1: make the support a planned amount
Irregular, reactive giving is the hardest to budget. A transfer here, groceries there, a sudden clinic bill. It adds up without you seeing the total.
Agree a regular monthly amount instead. Treat it like a bill: it leaves on payday, every month. Parents also find it easier to plan with a reliable amount than with unpredictable gifts.
For extra costs, such as medical bills or home repairs, decide in advance how you will handle them. You might keep a small separate fund for family emergencies.
Step 2: decide your order of priorities
When money is tight, an order helps you decide without agonising every month. One reasonable order:
- Essentials for your own household — housing, food, transport, minimum debt payments.
- A starter emergency fund — even one month of expenses.
- Regular support to parents — the agreed monthly amount.
- Your retirement savings — beyond mandatory contributions.
- Other goals — holidays, upgrades, a bigger home.
Everyone's order will differ. The point is to have one, so a request does not automatically push out your safety net.
Step 3: share the load with siblings
If you have brothers or sisters, talk openly about who contributes what. Unspoken expectations are a common source of resentment, especially when one sibling quietly carries most of the cost.
Contributions do not have to be equal in money. One sibling might give more cash, another might handle appointments, transport or caregiving time. Writing down the arrangement, even informally, keeps it fair and clear.
Step 4: understand what support already exists
Your parents may have savings or pension income you are not fully aware of. CPF payouts in Singapore, EPF savings in Malaysia, super and the Age Pension in Australia, or Social Security in the USA may provide some retirement income. Government schemes for older people, healthcare subsidies and tax relief for supporting parents may also apply.
These schemes and their rules vary and change, so check official sources in your country (for example the CPF Board and IRAS in Singapore, KWSP/EPF and LHDN in Malaysia, Services Australia and the ATO, or the SSA and IRS in the USA) for what applies to your family. A respectful conversation about what your parents already have can help everyone plan better.
Step 5: plan for healthcare
Medical costs are often the biggest unknown. Questions worth discussing as a family:
- Do your parents have health insurance, and what does it cover?
- Which clinics or hospitals do they use, and are subsidised options available?
- Who pays if a large bill arrives?
Having this conversation before an emergency is much easier than during one.
Step 6: protect your retirement too
Mandatory schemes like CPF, EPF, super or Social Security are a start, but may not be enough on their own for the retirement you want. Even a small extra amount each month, started early, adds up over decades. If you cannot save much now, set a date to review and increase it, such as after a pay rise or when a loan ends.
Have the conversation kindly
Talking about money with parents can feel uncomfortable. Some ideas that help:
- Start with care, not numbers: "I want to make sure you're comfortable, and that I can keep helping for a long time."
- Be honest about your own limits.
- Invite siblings into the conversation early.
- Revisit the arrangement once a year, or when circumstances change.
Try it in Financce
- Add your parents under More → Family → Add family member.
- Add your monthly support as a recurring bill in More → Bills and income, linked to them under For. You will be reminded each month.
- When you pay for groceries, clinic visits or other costs for them, choose them under For when adding the expense. Their Family screen shows the total spent on them.
- Create a goal in More → Goals for your own emergency fund, so it grows alongside the support you give.
- Check Reports every month to see how support fits into your overall spending.
This article is general information, not financial advice.
 Try it in Financce, the Goldmend Money app for everyday money. Get Financce
General information, not financial advice. Figures are examples.
Next: Planning for your children's education costs: from school fees to a university fund