Journal · Financce · Family money
Planning for your children's education costs: from school fees to a university fund
Understand education inflation, plan for school-term costs, and work out a monthly amount for a future university fund using simple, realistic steps.
 Goldmend Money
5 min read
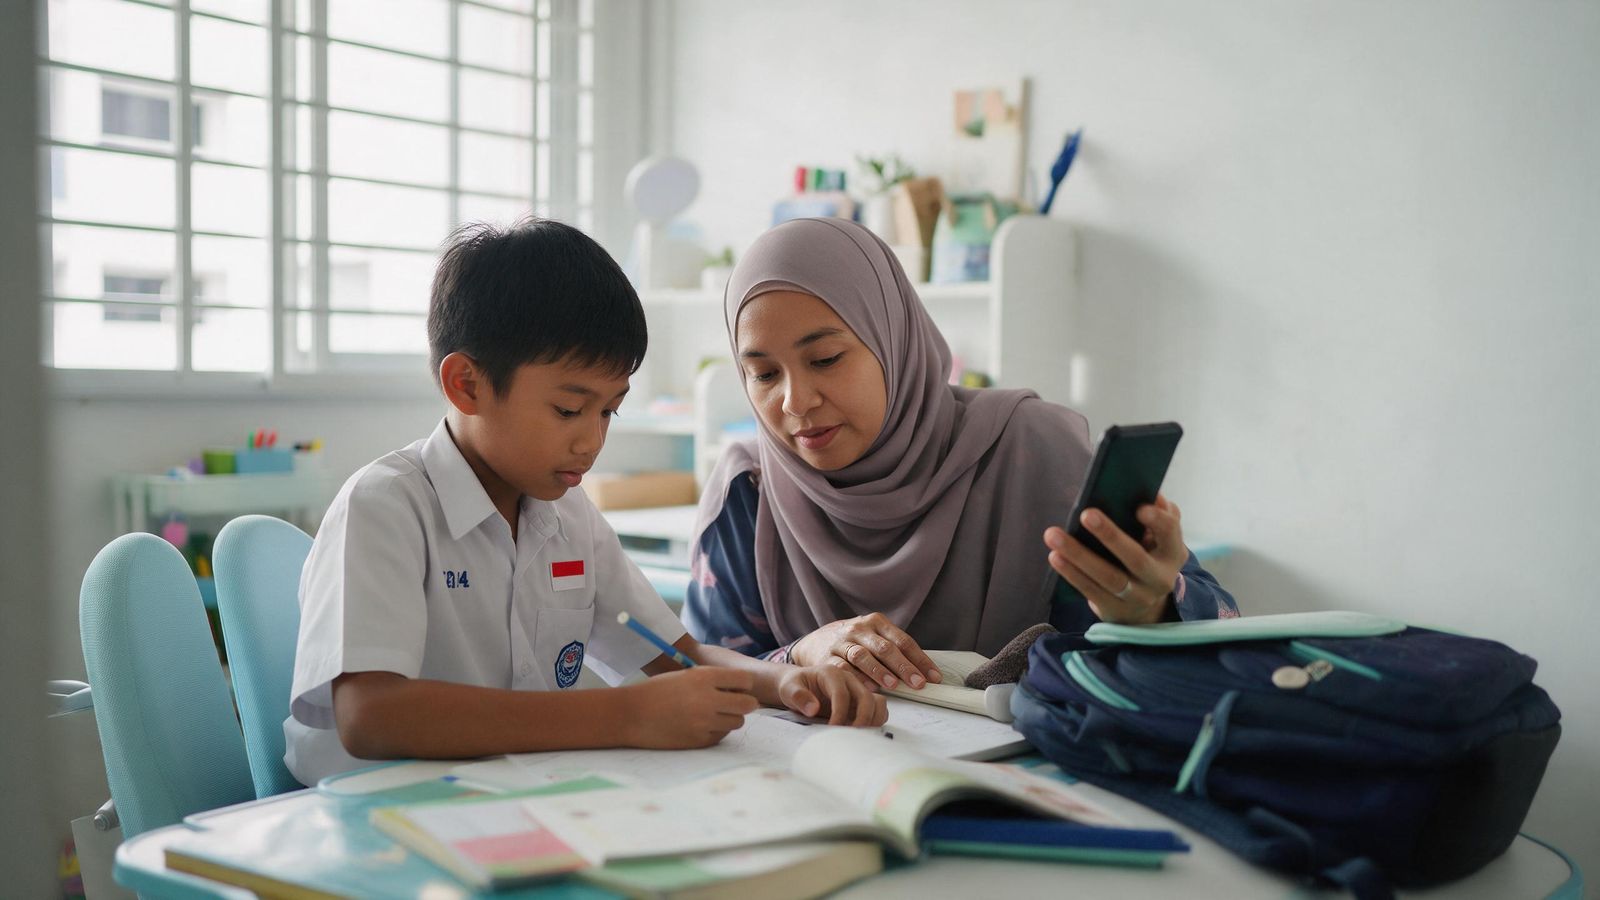
Education is one of the largest costs most parents face, and one of the hardest to plan. It arrives in two forms. There are the steady costs now: school fees, tuition, books, transport, enrichment classes. And there is the big future cost: college or university, possibly years away.
Both are easier to manage when you see them clearly.
Part 1: the costs you pay now
List everything, not just fees
School fees are only part of the picture. Make a full list for each child:
- school or kindergarten fees
- tuition and enrichment classes
- books, uniforms and stationery
- school transport
- canteen money
- trips, events and exam fees
- devices and internet for schoolwork
Note how often each one is paid: monthly, termly or yearly.
Spread the lumpy costs
Termly and yearly costs are the ones that cause stress. If the start of the year brings S$1,500 in books, uniforms and fees, that is S$125 a month if you start saving a year ahead. Figures are examples.
Setting these up as recurring bills means you see them coming instead of being surprised.
Part 2: the future cost of higher education
Why education inflation matters
Course fees tend to rise over time, and in many places they have historically risen faster than general prices. This is called education inflation. It means today's fee is not what you will pay when your child enrols.
A simplified example: suppose a degree costs S$80,000 today, including fees and living costs. If costs rise 5% a year, in 12 years that becomes roughly S$144,000. At 6% a year, it is about S$161,000. These are illustrations, not forecasts. Actual increases vary widely between local and overseas universities, public and private institutions, and courses.
Check the real fees for the kind of course you have in mind. University websites and official education portals are a good start.
Work out a monthly target
Once you have a future cost estimate, the question becomes: how much to save each month to get there?
You need four inputs:
- today's total cost of the course
- your child's age now and the age they will start
- an assumed rate of education inflation
- an assumed yearly return on your savings, if any
Be conservative with the return. No savings or investment return is guaranteed, and some options carry risk of loss. If you are unsure, plan with a low or zero return. You will over-save slightly rather than fall short.
Start early, even with a small amount
Time makes a big difference. Saving S$300 a month for 15 years puts S$54,000 of your own money aside. Starting five years later at the same amount, you put in S$36,000. Any growth on top widens the gap further.
If the monthly figure looks too high, do not give up. A partial fund still reduces future borrowing. You can increase the amount when income rises.
Look at other sources
Families often combine several sources: their own savings, scholarships, education loans, government schemes, and the student's own work. In Singapore there are bursaries, CPF education schemes and government-supported savings for children; Malaysia has SSPN and PTPTN; Australia has HECS-HELP loans; and the USA has 529 plans and federal student aid. Rules, eligibility and benefits vary and change, so check the official websites before relying on any of them.
Part 3: keep the plan alive
- Review once a year. Update the cost estimate and your savings.
- Adjust as plans change. Children's interests change. A plan for a five-year medical degree may become a three-year diploma, or the reverse.
- Do not raid it for everyday costs. Keep the fund separate from school-term money.
- Protect your own retirement too. Your child can borrow for education. You cannot borrow for retirement.
Try it in Financce
- Go to More → Education → Add school fee or class to add fees, tuition, lessons and transport as recurring bills, linked to each child. You get reminders before they are due.
- Add your children under More → Family to see costs By child.
- Tap Plan a university fund to open the Education fund planner. Enter today's total cost, your child's age now and at start, education inflation and an expected return.
- The planner shows the cost when the course starts and how much to save each month. Tap Create this savings goal to track it in Goals.
The planner's results are estimates based on the figures you enter.
This article is general information, not financial advice.
 Try it in Financce, the Goldmend Money app for everyday money. Get Financce
General information, not financial advice. Figures are examples.
Next: Work expense claims and side income: keep track so you never lose money