Journal · Financce · Debt
Understanding loans and instalments: monthly payments, flat vs reducing rates, in plain terms
What a monthly instalment really costs, why a flat rate is not the same as a reducing rate, and what to check before you sign any loan or instalment plan.
 Goldmend Money
5 min read
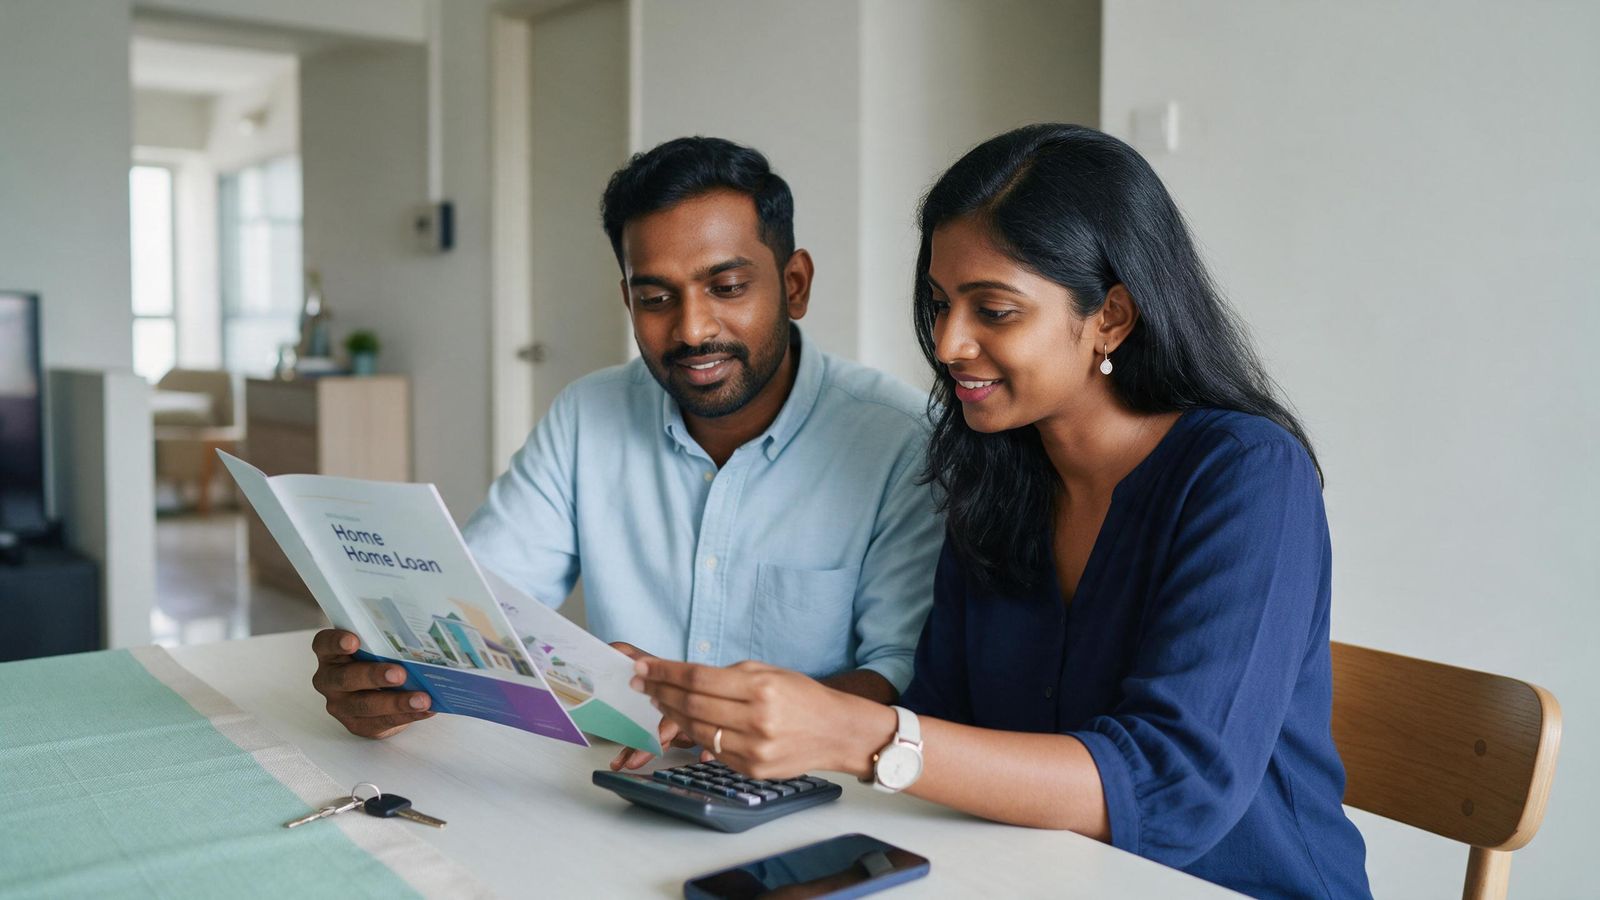
Car loans, personal loans, housing loans, "buy now, pay later", 0% instalment plans for phones and furniture. Borrowing is everywhere, and the numbers are often presented in ways that make the cost hard to see.
You do not need to be a maths expert to understand a loan. You need three ideas: the monthly instalment, how interest is calculated, and the total cost.
The monthly instalment
Most loans are repaid in equal monthly amounts. In some countries this is called the EMI, or equated monthly instalment. Each payment covers some interest and some of the original amount borrowed (the principal).
The monthly amount depends on:
- how much you borrow
- the interest rate
- how long you take to repay (the tenure)
A longer tenure means a smaller monthly payment, but more interest overall. This is the most common trade-off in borrowing, and it is easy to get wrong. A payment that "fits the budget" can still be very expensive in total.
Flat rate vs reducing balance rate
This is the part that confuses most people, and it matters a lot.
Flat rate
With a flat rate, interest is calculated on the original loan amount for the whole tenure, even though you are paying it down every month.
Example: borrow S$30,000 at a 3% flat rate for 5 years.
- Interest per year: S$30,000 × 3% = S$900
- Total interest: S$900 × 5 = S$4,500
- Total repaid: S$34,500
- Monthly instalment: S$34,500 ÷ 60 = S$575
Flat rates are common for car loans and some personal loans in Singapore and Malaysia.
Reducing balance rate
With a reducing balance (or effective) rate, interest is calculated only on what you still owe. As you repay, the interest portion shrinks.
Housing loans are usually calculated this way.
Why the difference matters
A 3% flat rate is not the same as 3% on a reducing balance. Because flat-rate interest is charged on money you have already repaid, the true cost is higher. In the example above, a 3% flat rate over five years works out to roughly 5.6% on a reducing balance basis.
So when comparing loans, compare like with like. Ask the lender for the effective annual rate, or compare the total amount you will repay. Figures here are examples; your loan's terms will differ.
"0% instalment" plans
Interest-free instalments for phones, laptops and appliances can be genuinely useful. Before you agree, check:
- Is there a fee? Some plans charge an upfront or monthly fee instead of interest.
- Is the price the same as paying in full? Sometimes the instalment price is higher.
- What happens if you miss a payment? Late fees and interest may apply.
- Does it lock up your credit limit? On a credit card, the full amount may be blocked from your limit.
Most of all, remember that an instalment is a commitment for months or years. Several small ones can add up to a large fixed cost.
Buy now, pay later
BNPL services split purchases into a few payments. They are convenient and easy to over-use, because each purchase feels small. Treat each BNPL plan as a bill with a due date and an end. Rules and protections for BNPL are developing in the region, so check consumer guidance from Bank Negara Malaysia or MAS.
Before you sign any loan
Ask yourself and the lender:
- What is the total amount I will repay, including all fees?
- What is the effective annual interest rate?
- Is there a penalty for paying early or settling the loan in full?
- What happens if I miss a payment?
- Can I afford this payment if my income drops for a few months?
A useful rule of thumb many people use is to keep total monthly debt repayments well below a third of take-home pay. Lenders apply their own limits. Your comfort level may be lower.
Paying off faster
If you can pay extra, check whether your loan allows it without penalty. On a reducing balance loan, extra payments directly reduce the interest you pay. On a flat-rate loan, early settlement may give you a rebate on future interest. The rules vary by loan type and country, so check your agreement.
Try it in Financce
- Open More → Calculators → Loan / instalment to see the monthly payment and total interest on a loan. Try different tenures to see how total cost changes.
- Add each loan or instalment plan in More → Bills and income. Turn on Instalment plan with an end and enter Payments left. The list shows how many are left, and the plan stops after the last one.
- Tap Mark as paid each month. Financce logs it and moves to the next due date.
- Check More → Schedule to see upcoming payments alongside your income.
This article is general information, not financial advice.
 Try it in Financce, the Goldmend Money app for everyday money. Get Financce
General information, not financial advice. Figures are examples.
Next: Save on groceries with unit pricing: how to spot the real bargain on the shelf