Journal · Financce · Family money
Lending money to friends and family without losing either
How to decide whether to lend, agree clear terms without awkwardness, keep track of repayments, and protect the relationship if it goes wrong.
 Goldmend Money
4 min read
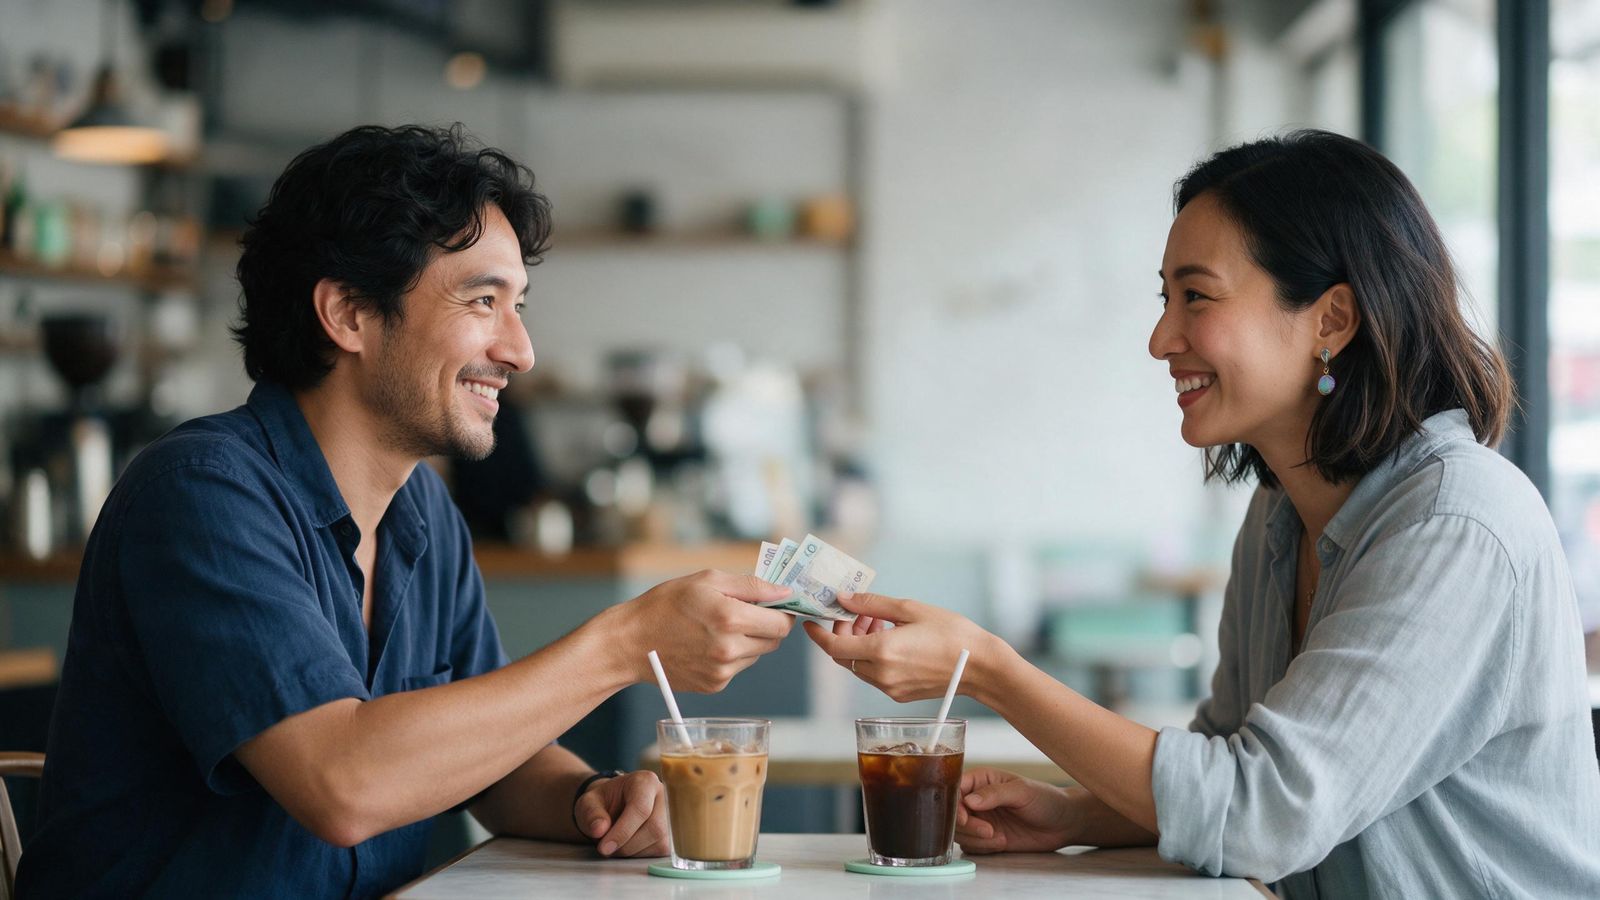
Sooner or later someone close asks to borrow money. A cousin is short on rent. A friend needs help with a car repair. A sibling is starting a small business.
In many Southeast Asian families, saying no feels impossible. Saying yes without a plan can cost you both the money and the relationship. There is a middle path.
Decide before you are asked
The hardest time to think clearly is in the moment, with someone you love waiting for an answer. Decide your own rules now:
- the most you are willing to lend to any one person
- whether you lend for some purposes (medical, education) and not others (holidays, gadgets)
- whether you lend at all if an earlier loan is still unpaid
Having a rule makes it easier to say "I can do S$500, not S$3,000" without it feeling personal.
Only lend what you can afford to lose
This is the most important principle. Assume there is a real chance the money will not come back on time, or at all. If losing it would hurt your rent, your emergency fund or your own debt payments, lend less or not at all.
If you want to help but cannot afford to lose the amount, consider giving a smaller sum as a gift instead. A gift has no repayment, no reminders and no resentment.
Agree the terms clearly
Most money fights come from fuzzy expectations, not bad intentions. Before handing over money, agree:
- how much, exactly
- when it will be paid back, or in what instalments
- how — bank transfer, cash, e-wallet
- what happens if a payment is late
Keep the tone warm and practical: "Just so we're both clear, let's say S$300 a month from March. I'll send a quick message when it's due so neither of us forgets."
For larger amounts, a short written note or a message thread confirming the terms helps both sides remember. For significant sums, especially anything related to property or business, it may be worth getting proper legal advice.
Keep a record
Memory is unreliable, especially across months and multiple small repayments. A record protects both of you. You will not under-count what was paid back, and they will not feel accused when you check.
Record the original amount, the date, and every repayment as it arrives. Partial payments count.
Following up without drama
If a payment is late:
- Send a friendly reminder a few days after the due date.
- If nothing comes, ask directly whether something has changed. Life happens.
- Offer to adjust the plan, such as smaller payments over a longer time.
Avoid raising it in front of other people. Public pressure rarely gets money back, and it often ends relationships.
When you are the borrower
The same rules apply the other way round. Borrow only what you have a clear plan to repay. Propose the terms yourself. Pay on time, and if you cannot, say so before the date, not after. Being a reliable borrower keeps doors open for both of you.
When to let it go
Sometimes the money is not coming back. At that point, decide whether the relationship matters more than the amount. Many people find it healthier to call it a gift in their own mind, stop chasing, and simply not lend again.
That is a valid choice. It is easier to make when the amount was one you could afford to lose in the first place.
Try it in Financce
- Go to More → Debts and IOUs and tap +.
- Choose I lent money (or I borrowed if you are the one repaying).
- Enter who it is with, the amount and what it was for.
- Tap Add a pay-back date if you agreed one.
- When money comes back, open the entry and record the payment. Partial payments are fine.
The top of the screen shows Owed to you and You owe at a glance. Paid-off entries move to Settled, so you keep a history without clutter.
This article is general information, not financial advice.
 Try it in Financce, the Goldmend Money app for everyday money. Get Financce
General information, not financial advice. Figures are examples.
Next: Family budgeting with kids: tracking costs per child and teaching with pocket money